
What Goes Into an Annual Portfolio Review?
Four things change measurably in a year across an ISA, a pension, a dealing account and some cash: the allocation you can only see by add...
· 12 min read
Brand Finish
Asset allocation, diversification, rebalancing and investor behaviour, tested on long-run data. What each choice has cost and returned.
Four things change measurably in a year across an ISA, a pension, a dealing account and some cash: the allocation you can only see by add...

The S&P 500 lost 33.92% in 23 trading days and needed 126 to get it back. In sterling, global equities fell 26.04% and a 60/40 of world e...

In 2022 the FTSE All Share returned 0.70% and UK gilts lost 24.00%, so for a sterling investor the crash was almost entirely on the bond ...

A decade of zero equity returns is the mild version. In Shiller's US data, 193 ten-year windows since 1881 delivered nothing or less from...

Over the hundred years to September 2026, 29.5% of one year holdings in US shares lost money after inflation and none of the 843 thirty y...

Across 1901 to 2020 the shallowest worst year of six global stock and bond mixes belonged to the one holding 20% equities, at -21.2%. All...

In the third quarter of the 2025 to 2026 financial year, 11.8% of newly enrolled savers left within a month. That is why the figure writt...

India's regulator compared first time derivatives traders with repeat traders in the year to March 2026 and found 87.81% of the newcomers...

In US workplace plans the equity share runs from 88% under 25 to 45% at 70 and over. In UK ISAs, where nobody is defaulted into a glide p...

Most of what a house purchase costs is paid at completion, so a collapsed chain never reaches it. What you lose is the survey, the search...

In December 2024 the average UK new build sold for £332,197 and the average existing home for £260,674. Part of that £71,523 gap buys a w...

The mortgage payment is the number everyone uses for what a house costs, and it is wrong twice. £122.10 of the average £224.40 weekly pay...
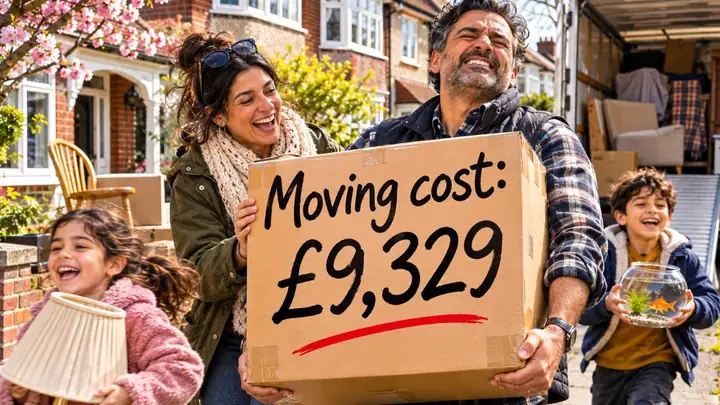
A same-price move on the UK average home of £273,000 costs £9,329 in stamp duty, agency commission and the registration fee. That is 3.42...

Build the rent versus buying comparison properly and one input does most of the work. Across the range UK house prices have actually deli...

Long-run housing returns are price growth plus rent. A second home you keep for yourself collects the price leg and almost none of the re...

A pension can buy the building your business trades from, and the rent lands untaxed. The rules on what counts as commercial are unforgiv...

A driveway of any size is permitted development in England if the water can drain away. The 5 square metre rule bites only on impermeable...

Nationwide's series shows UK house prices compounding at 5.8% a year from 1995 to 2025. On a 75% mortgage at the period's average 2-year ...

There is no percentage cap on a variable service charge in England. The limit is that costs must be reasonably incurred, and the record s...

Across 18 advanced economies from 1950 to 2020, real house prices rose an average 0.5% in the years inflation ran above 10%, and rose in ...

Legal & General's own table puts £50,000 at 7% at £193,484 after 20 years. UK house prices grew 2.66% a year over the last two decades. T...

Downsizing releases the gap between two houses, not the sale price. On Nationwide's Q2 2026 UK averages a detached to semi-detached move ...

Fama and French added profitability and investment to their three-factor model in 2015. On portfolios sorted by those two variables the a...

Kenneth French publishes the same five factors for developed markets outside the US and for emerging markets. Over the 409 months to July...

A multi-factor fund promises value, size, quality and momentum. Regress five well-known US ones on the Fama-French factors and the value ...

Equal weight beat cap weight by 271 basis points a year from 1967 to 2009. Only 81 of those points came from the size tilt. The value til...

Buying a factor when it's cheap and selling it when it's expensive is the oldest idea in factor investing. Run 12 versions of it on 69 ye...

Five iShares factor ETFs tracked their index to within 0.21 percentage points a year since launch. The indices themselves are a different...

Healthcare returned 11.57% a year over the 100 years to July 2026 and telecoms 8.80%. That narrow spread hides the fact that every one of...

DeMiguel, Garlappi and Uppal found in 2009 that no optimiser beat a simple even split. Run the same test on 10 asset menus and 259 months...

Split 72 years of US returns by the direction of the 10-year yield and the stock bond correlation barely budges: +0.05 rising, +0.12 fall...

Across every developed-equity fall of 20% or more since July 1990, a standard trend following rule gained money six times out of six, by ...

A 60/40 multi-asset fund looks through to 12,261 holdings held via four index funds. Measured on 98 years of US returns, 93.7% of its var...

Over 655 months since 1972, gold's correlation with US equities was 0.01. In the worst 5% of those months it rose to 0.31 rather than tur...

Over the 420 months from January 1991 to December 2025, adding emerging markets to developed equities at 5%, 10% and 20% raised annualise...

A ten-rung gilt ladder priced on the Bank of England's curve for 8 September 2026 carries 4.61 years of modified duration. The all-stocks...

Correlations between the US and the rest of the developed world did converge, and then they stopped: the 60-month rolling figure peaked a...

One stock, most of your net worth, and a capital gains bill in the way. Staged selling, exchange funds and collars all promise a way out....

A REIT fund is sold as property, a different asset from the shares you already own. Measured over 521 weeks of returns to September 2026,...

Ten lines on a factsheet carry 26.61% of the MSCI World Index. In October 2015 they carried 9.77%, and the index held 362 more companies....

Over 155 years of US data, a longer holding period cut the spread of annualised real returns by a factor of six and widened the spread of...

MSCI publishes the same global index in local currency terms and in each base currency, which lets you split a foreign equity return into...

Fifteen candidate sleeves, each added at 10% to the same 60/40, over 433 months of monthly returns. The best raised the Sharpe ratio by 0...

Over 100 years of US data the smallest companies compounded 1.48 points a year faster than the biggest. Strip out January 1975 to June 19...

Moving to cash when the market is 20% down beat staying invested at the eventual trough in 8 of the 10 US bear markets since 1926. Measur...

Gold beat US inflation in 53.1% of one-year windows since 1975, 52.2% at five years and 53.4% at ten. At twenty years it was 62.4%, and m...

Index domestic equity funds held 19% of the value of US stocks at the end of 2025, and all passive investors together held about a third....

Harry Browne's four-way split returned 7.44% a year from 1980 to 2025 against 10.24% for a 60/40. That gap is the price of a worst year o...

UK mortgage holders paid £224.40 a week in 2024-25 and only £122.10 of it built equity. Once upkeep, stamp duty and the deposit's forgone...

Emerging economies really do grow faster, by 2.5 percentage points in 2025 on the IMF's numbers. Across ten of those markets, the correla...

Tilt size decides one thing with certainty: tracking error. Over the century to June 2026 a 20% small cap tilt bought 3.14% of it, a 5% t...

MSCI World held 28.87% in one sector on 31 July 2026. Every diversification rule that binds a fund caps issuers, not sectors, and the ind...

A 5 percentage point tolerance band is not one rule. On a 60% equity sleeve it fires on a 23.8% relative move; on a 5% gold sleeve it nee...

Risk parity looks best on paper because the paper does not charge for the borrowing. Financed at Treasury bills, it beat the US market by...

Varying a UK investor's home weight from 0% to 100% against MSCI World barely moves portfolio volatility across the middle: 9.55% to 10.0...

One global index fund held 7,500 stocks at 31 July 2026 for a 0.23% charge. The factsheet arithmetic from 1 fund to 20 shows most additio...

Three inflation hedge assets met one real inflation shock between 2021 and 2025. Commodities paid while prices were rising, gold paid onl...

Yale's reported ten-year lead over a typical 70/30 portfolio fell from 3.8 percentage points a year to 2.2 between two consecutive annual...

Hedged and unhedged versions of the same global index differed by 0.26 percentage points a year in sterling and 7.85 in yen over the deca...

A permanent 10% cash sleeve cost a 60/40 portfolio 0.49 percentage points of real return a year over 92 years. That average is made of er...

Rebuilt from Kenneth French's CRSP data, equal-weighting the largest 30% of US stocks returned 12.04% a year over the 50 years to June 20...

A glide path from 75% equities to 36% and a fixed 55.5% weight hold the same average equity over a working life. Across 59 overlapping 40...

An age rule answers the allocation question with a percentage. Liability matching answers it with a price. The income a 55-year-old needs...

Bridgewater publishes the All Weather concept as a risk diagram with no weights and no returns. Rebuilding it from six US-listed ETFs giv...

No paper derives 60/40. The trail runs to a fund launched in 1929, a 1952 theory that hands you a curve instead of a number, and pension ...

Your fund lagged for three years and the one at the top of the table didn't. On Morningstar's data to June 2026, a randomly chosen active...

Manager tenure is on every factsheet because the SEC made it mandatory in 2004, not because it forecasts anything. In the studies that pu...

A 40/60 portfolio levered 1.5 times holds the same 60% in equities as a plain 60/40, and 50 extra points of bonds. In 2022 that cost 8.13...

Morningstar's own study of 43,698 funds found 5-star funds beat 1-star funds by about 0.25 percentage points a year. Vanguard measured th...

Of the 2,376 US domestic equity funds you could have bought at the start of 2005, 36.41% were still running twenty years later. The recor...

The last redoubt of active management is the claim that it works where markets are less efficient: small caps and emerging markets. Over ...

Regulators who went looking for closet indexing found it: ESMA flagged up to 15% of EU equity funds as potential closet indexers, and the...

The FCA regressed UK active fund performance on charges twice. Before fees, the relationship was statistically invisible. After fees, it ...

Sort every active fund into quartiles, wait five years, and sort again. Only 11.79% of top-quartile US equity funds stayed on top, while ...

A fund that doubles in size trades worse. The best estimates put that cost between 65 basis points and 2% a year before fees, and only in...

Two real published factsheets, read line by line. The 0.19% charge that excludes dealing costs, the benchmark that comes in two versions,...

Banz documented the size effect in 1981, making it the oldest anomaly in finance. Since April 1981 the Fama/French size factor has compou...

Sort US stocks by beta and the riskiest tenth has returned less than the safest tenth since 1963 — 9.53% a year against 10.79%, at more t...

Index funds lend their holdings out for a fee, and the manager keeps a share of it. That share runs from 7.7% at Vanguard's Irish range t...

An ETF tracks its net asset value because a handful of firms can swap the fund for its contents. They are not obliged to. Grayscale's bit...

Momentum is the largest of the classic equity factor premiums — 6.19% a year in the Fama/French series since 1927, against 3.59% for valu...

A swap-based ETF exposes you to a bank. UCITS caps that exposure at 10% of assets, and the big providers reset it to zero every trading d...

In 2022 US equity REITs returned -24.95% and the appraised MSCI UK Annual Property Index returned -7.1%. Almost none of that gap is the b...

Two S&P 500 ETFs, one charging 0.03% and one charging 0.12% all-in. In calendar 2025 the expensive one beat the index by 0.32 points and ...

Fama and French documented the value premium in 1992. Their own HML series compounded at 4.84% a year across the sample they studied, and...

Calendar vs band rebalancing: from 1972 to 2014 an annual rebalance scored a 0.43 Sharpe ratio against 0.40 for a 20% tolerance band at t...

How much of a portfolio should be in bitcoin? A 5% sleeve added 3.19 points a year to a 60/40 from 2015 but subtracted 1.68 from 2025. Al...

The rebalancing bonus: in Vanguard's 92-year test a yearly rebalanced 60/40 returned 8.19% against 8.74% never rebalanced, with lower vol...

Position sizing when an asset can go to zero: a total loss at 5% weight needs a 5.26% gain elsewhere. What Bessembinder, Kelly and Thorp ...

How often should I check my portfolio? In a 1997 experiment, people shown results every round bet 50.5% of their stake; every third round...

Performance chasing: specialised ETFs lost about 30% risk-adjusted in their first five years, and no 2022 top-quartile large-cap fund kep...

Overconfidence in investing: in Barber and Odean's study of 35,000 households, men traded 45% more than women and cut net returns by 2.65...

Lump sum vs cost averaging: a lump sum beat phasing in 61.6% to 73.7% of the time across markets, 1976 to 2022. Plus the median gap and w...

Loss recovery is slow: US shares lost 50.1% in real terms in 1973 to 1974 and took twelve years to recover. Recovery times since 1871, bo...

The famous 2.25 loss aversion figure came from 25 students in 1992; 607 later estimates average 1.96. Plus a re-cut at 1.07 and who is lo...

Risk contribution: adding gold, property and crypto to a 60/40 cut modelled volatility from 15.7% to 12.4%, yet equities still supplied 7...

Equity allocation and crash depth: from the 1929 peak, 100% equities fell 64.8% and 60/40 fell 40.1%. Plus why extra bonds bought no fast...

Should I sell my company shares? Only 42.6% of US stocks beat Treasury bills over their lives; one estimate puts the cost of employer sto...

How many stocks is diversified? The 30 to 40 answer came from a 1987 paper on volatility alone, yet 4.31% of US firms created all net sto...

The disposition effect: investors realise 14.8% of paper gains but only 9.8% of paper losses, and sold winners beat held losers by 3.4 po...

Buying the dip vs steady investing: over 100 years, waiting for 30% falls left 84% of what monthly investing built, and 97% at a 10% trig...

Currency hedging cut a sterling investor's global bond volatility from 10.35% to 5.40% over 1975 to 2005, but raised it on world shares. ...

Crypto rebalancing with a 5% band on a 5% bitcoin sleeve fired 516 times in ten years, against five on equities, for no extra return. Plu...

Correlation instability: a fixed 0.50 correlation reads 0.21 in calm months and 0.62 in volatile ones. Plus why bond-stock correlation fl...

Sizing a core-satellite portfolio: a 10% bitcoin satellite supplied 28.1% of variance over ten years; gold at 10% supplied 2.2%. Plus tra...

Rebalancing without selling: pointing new money at the lagging side holds a 60/40 on target until the pot passes about 17 times annual sa...

Cash drag: US bills returned 0.5% a year after inflation since 1900 against 6.6% for shares, so 10% in cash costs 0.61 points a year. Plu...

At 65 the 100 minus age rule puts 35% in shares, where Vanguard's glide path holds 50%. Also covered: T. Rowe Price's path, human capital...

Eight major US drawdowns from the December 1968 peak onward. The median took 31.5 months to reach a new high in nominal price terms and 6...

Across the six times developed-world equity fell 20% or more since 1990, 10-year Treasuries and Treasury bills carried almost all of the ...

US stocks in the 1970s and the 1980s had annualised standard deviations of 13.41% and 13.17% — as close to identical as two decades get. ...

Five funds — a total-market fund, an S&P 500 fund, a growth fund, a tech fund and an innovation fund — hold 1,533 companies between them,...

The United States was 62.09% of world equity value at 30 June 2026; Australia was 1.56%. That single fact makes the home-bias question a ...

Across 16 countries since 1870, housing's real total return of 7.05% a year edged equities' 6.89% with less than half the volatility. Tho...

An investment policy statement is a rule written before the decision arrives. CFA Institute lists 16 elements, CalPERS runs 120 pages, an...

A 60/40 portfolio left alone ends the year a median 3.2 percentage points off target. But the distribution is lopsided: the biggest singl...

Equities are down 30% and a 60/40 has drifted to roughly 50/50. Moving it back to target beat leaving it alone in both October 2008 and M...

A questionnaire says you are 'moderate'. It's measuring how you feel about risk, not how much of it your plan can absorb, and those answe...

Run 30 years of real US 60/40 returns forwards and backwards. A $1,000,000 lump sum left alone ends at exactly $5,116,739 either way. Add...

Three funds at Vanguard's own 60/40 target weights returned 6.44% a year from 2008 to 2025, or 3.91% after inflation. Nominally 2008 was ...

The folklore says your own timing costs you 4% a year. Morningstar's data says 1.2%. A 2026 Financial Analysts Journal paper says the par...

Over 92 years of Vanguard's data, every sensible rebalancing rule landed within 0.2 percentage points a year of every other one. The choi...